The tax reform will replace all consumption taxes with a VAT (value-added tax), paid by the final consumer, charged non-cumulatively at all stages of the production chain.
The five current consumption taxes (IPI, PIS, Cofins, ICMS and ISS) are replaced by two consumption taxes (IBS and CBS) and a Selective Tax (IS).
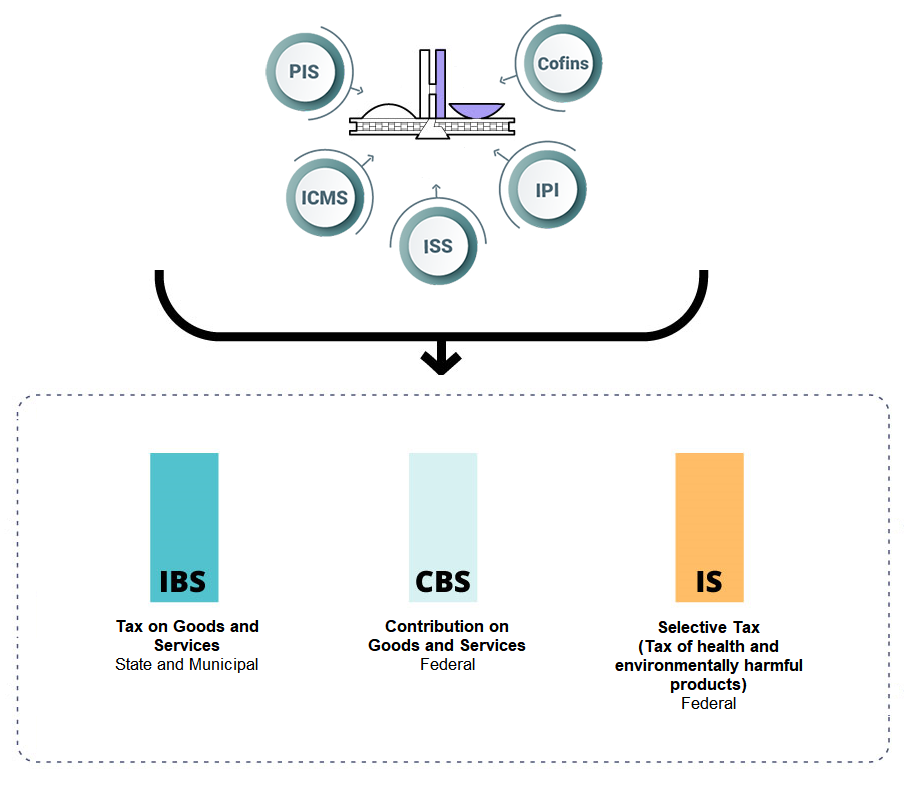
IBS (Tax on Goods and Services) / CBS (Social Contribution on Goods and Services)
Under Constitutional Amendment 132/2023 and Complementary Law 214/2025, IBS and CBS have the following characteristics:
- They are charged on all operations with tangible or intangible goods and services
- They are charged at all stages of the production chain, giving the right to credit for the previously paid tax (non-cumulative)
- They are not charged on exports
- They are charged on imports
- They adopt the principle of destination (rate and collection linked to the place of consumption)
- Provide for a single rate for all goods and services consumed in each location
- Due to the particularities of certain sectors, differentiated taxation regimes are foreseen for:
- Financial services, real estate, fuel, public sector procurement, health care plans, prediction contests, cooperatives, and hotels, bars, restaurants and tourism
- There are plans for special treatments to reduce the impact of changing the model:
- 60% reduction of IBS and CBS rates for:
- urban, semi-urban or metropolitan public transport services;
- medicines;
- medical devices and healthcare services;
- education services;
- agricultural, fishing, forestry and plant extractive products in natura;
- agricultural inputs, food intended for human consumption and personal hygiene products
- national artistic and cultural activities
- exempt public urban, semi-urban or metropolitan transport services;
- reduce by 100% the rate of CBS and IBS levied on certain medications;
- reduce by 100% the CBS rate levied on higher education services (PROUNI)
- 60% reduction of IBS and CBS rates for:
- Complementary Law 214/2025 defines the sectors that have differentiated treatment;
- Provide for the maintenance of the global tax burden on consumption
- Makes taxation on consumption less unfair, as they adopt the possibility of refunding the tax (cashback). In this way, the granting of tax benefits is focused on those who need it most, in contrast to the option for exemptions by type of merchandise.
- Preserve Simples Nacional and the favored treatment of the Manaus Free Zone
- Maintain constitutional bonds and divisions, such as Health and Education
- Contain transitional rules, shorter for society in general (taxation regime) and longer and smoother for sharing with states and municipalities (sharing system). 2026 is a test year (CBS 0.9% and IBS 0.1%, with payment waived for taxpayers that meet the ancillary obligations); in 2027 the CBS is charged in full, PIS and COFINS are extinguished and IPI is reduced to zero (except for products made in the Manaus Free Zone); from 2029 to 2032 ICMS and ISS are progressively reduced (by 10% in 2029 up to 40% in 2032) as the IBS increases; in 2033 ICMS and ISS are extinguished and the new model is fully in force
IS (Selective Tax)
The Selective Tax will be charged to discourage the consumption of goods and services harmful to Health and the Environment: vehicles, vessels and aircraft, tobacco products, alcoholic beverages, sugary drinks, mineral goods, and prediction contests and fantasy sport. It is scheduled to start in 2027; its rates still have to be set by ordinary law.